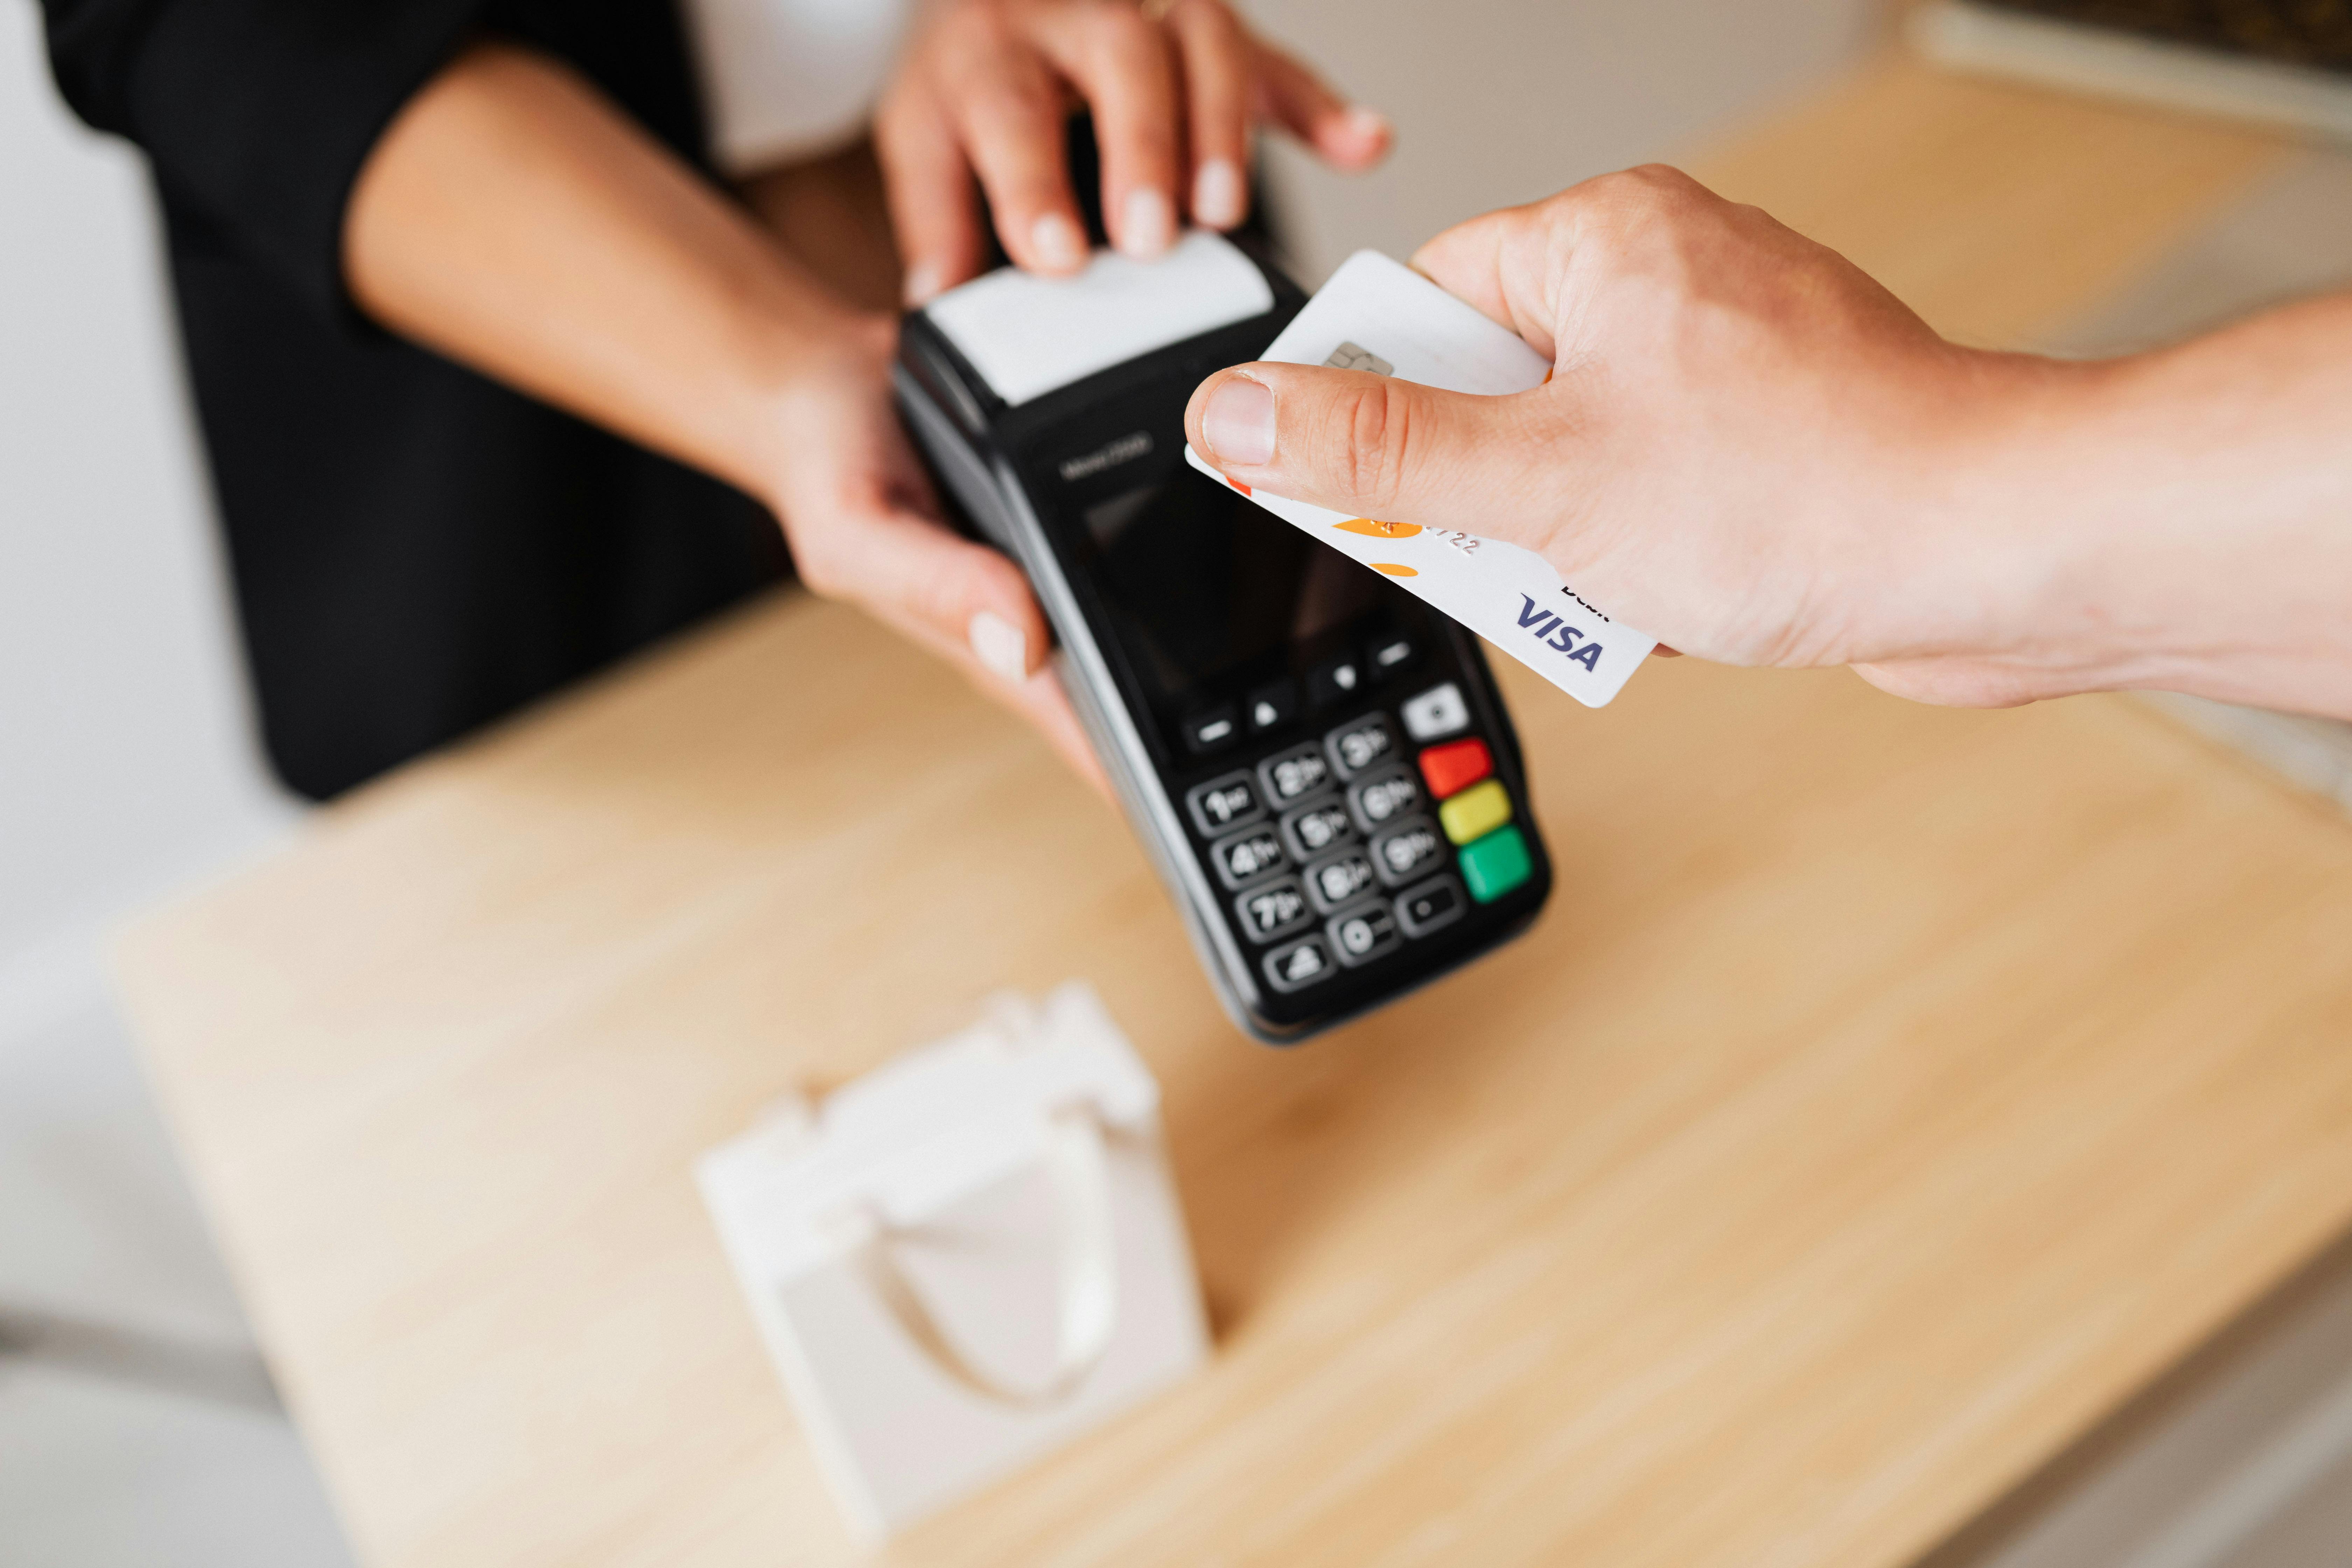
Every transaction matters. Whether a customer taps a card at the counter, pays an invoice remotely, or checks out on your website, reliable credit card processing helps keep your business moving. The right payment setup does more than authorize transactions: it can simplify checkout, support reporting, connect with your point-of-sale (POS) system, and make processing costs easier to understand.
Gratitude Merchant's approach focuses on helping businesses evaluate competitive processing options and practical payment technology. Rather than assuming every merchant needs the same setup, we start with how you sell, the tools you use, and what matters most to your operations.
What Is Credit Card Processing?
Credit card processing is the system that allows a business to accept card payments and receive funds from approved transactions. It connects the merchant, payment technology, processing partners, card networks, and the customer's card-issuing bank.
A customer can pay with a physical card, a contactless wallet, or card details entered online. Behind the scenes, the payment is securely transmitted for authorization. Approved transactions are then submitted for clearing and settlement, and funds are deposited according to the merchant's funding schedule, less applicable fees or adjustments.
How Credit Card Processing Works
- Customer makes a payment. A customer inserts, taps, swipes, or enters payment details through a compatible terminal, POS system, website, or invoice payment link.
- Transaction is authorized. Payment information is transmitted through the appropriate payment systems to the card issuer, which approves or declines the transaction.
- Transaction is captured and settled. Approved payments are captured and submitted for clearing and settlement. Depending on the setup, this may occur automatically or as part of a batch process.
- Your business receives funds. Funds are deposited to the designated business bank account based on the provider's settlement and funding terms. Actual timing can vary by provider, bank, transaction type, weekends, holidays, and risk review.
Payment Solutions for the Way You Sell
In-Person Card Payments
Make checkout convenient with compatible countertop terminals, mobile card readers, and modern POS systems. Support chip cards and contactless payments, including eligible digital wallets, with hardware and software suited to your business.
Online Payment Processing
Accept payments through an e-commerce checkout or secure hosted payment page. A payment gateway can connect your website to processing services, helping customers complete purchases without visiting a physical location.
Mobile and On-the-Go Payments
For businesses that work at customer locations, events, or job sites, mobile payment tools can help you accept eligible card payments wherever supported connectivity is available.
Virtual Terminal and Remote Payments
A virtual terminal lets authorized staff manually enter card payments through a secure interface when customers are not physically present. Because keyed transactions may have different costs and fraud risks, the right safeguards and procedures matter.
Integrated POS and Business Tools
Connect payment acceptance with compatible POS features such as sales reporting, inventory, employee management, tipping, or customer records. Feature availability depends on the platform and integration. See our POS systems.
Understand Your Credit Card Processing Fees
Processing fees can affect margins, especially as transaction volume grows. Comparing only an advertised rate may hide important differences in total cost. A meaningful review should consider your actual card mix, average ticket, monthly volume, sales channels, and the full merchant agreement.
Interchange-Plus Pricing
This model typically separates card-network interchange and assessment costs from the processor's markup. It can make individual cost components easier to identify, although total expenses still depend on transaction characteristics and other fees.
Flat-Rate Pricing
A single published rate or rate-plus-fixed-fee structure can be straightforward to understand. It may be convenient for some businesses, but it is not necessarily the lowest-cost option at every sales volume or card mix.
Tiered Pricing
Transactions are grouped into rate categories, often labeled qualified, mid-qualified, and non-qualified. The criteria and costs can be harder to compare across providers, so review the full schedule carefully.
Fees Beyond the Transaction Rate
Ask about monthly account charges, gateway subscriptions, PCI-related fees, chargeback fees, equipment purchases or leases, early termination terms, and other applicable costs. Request a clear written breakdown before signing.
Why the Right Processing Setup Matters
- Competitive cost structure. Evaluate pricing based on your real transaction profile, not just a headline percentage. The goal is a sustainable setup with transparent terms and predictable operating costs where possible.
- Faster, smoother checkout. Modern payment terminals and POS integrations can reduce friction at the counter and give customers convenient ways to pay.
- Flexible payment acceptance. Support in-store, online, mobile, and remote transactions using tools that fit your business model.
- Better operational visibility. Compatible dashboards and POS reports can help you review sales activity, reconcile transactions, and understand trends.
- Security-focused technology. Look for EMV-capable devices, encryption, tokenization where supported, access controls, and a provider that helps explain applicable PCI DSS responsibilities. No payment solution eliminates fraud or compliance obligations.
- Room to grow. As your business expands, your payment setup should be evaluated for additional registers, locations, integrations, or sales channels.
Credit Card Processing for Different Industries
Retail Stores
Support efficient checkout, contactless payments, refunds, and compatible inventory or sales reporting tools.
Restaurants and Cafés
Consider tableside or counter payments, tipping workflows, and POS features that match your service model.
Nail Salons and Beauty Businesses
Explore appointment-friendly POS systems, tipping, staff-level reporting, and convenient payment experiences.
Professional and Field Services
Use invoices, mobile readers, or secure payment links to collect payments in the office or on the go.
E-Commerce Businesses
Connect your storefront to an appropriate gateway and payment processor while considering fraud controls, recurring billing needs, and checkout experience.
Security and Payment Protection
Protecting payment data is an ongoing responsibility shared across merchants and service providers. Depending on your setup, relevant safeguards may include EMV chip technology, encrypted transmission, tokenization, fraud-screening tools, role-based access, software updates, and adherence to applicable Payment Card Industry Data Security Standard (PCI DSS) requirements. For more on this, read What Is PCI Compliance?
Businesses should also understand chargeback procedures, refund policies, and the risks of card-not-present transactions. Choose solutions that support good security practices and provide clear guidance on the responsibilities that remain with your business.
How to Choose a Credit Card Processing Provider
A good provider should fit both your budget and daily workflow. Before making a decision, ask for a full written pricing proposal and review the equipment, software, service, and contract terms together.
- What is the estimated total monthly cost based on my actual processing statements?
- Which fees are charged per transaction, monthly, or only in special circumstances?
- What hardware, POS software, gateways, and integrations are supported?
- How long does funding typically take, and what can delay deposits?
- What are the contract duration, cancellation terms, and equipment ownership conditions?
- How are chargebacks, technical issues, and support requests handled?
- What PCI DSS responsibilities and security features apply to my setup?
Our Approach to Merchant Processing
We believe payment processing should fit your business—not force your business into a one-size-fits-all system. Our approach starts with understanding your current processing costs, sales channels, transaction patterns, and technology needs. From there, we help you evaluate suitable payment acceptance and POS options, with attention to transparent pricing and long-term practicality.
Whether you are opening your first location, upgrading outdated terminals, expanding online, or reviewing an existing merchant account, a thoughtful processing review can reveal opportunities to simplify operations and make better-informed decisions. See our processing options.
Frequently Asked Questions
What is the difference between a payment processor and a payment gateway?
A payment processor helps route and manage card transactions through the payment ecosystem. A payment gateway securely transmits payment information from a website or other payment interface to the relevant processing services. Some providers package both capabilities together.
How much does credit card processing cost?
Costs depend on the provider, pricing model, card types, transaction method, average ticket, volume, and additional service fees. A statement-based comparison is more useful than relying on a single advertised rate.
How long does it take to receive card payments?
Funding schedules vary. Some providers offer next-business-day or other accelerated funding for eligible merchants, while others take longer. Cutoff times, holidays, bank processing, and account reviews can affect deposit timing.
Can I accept contactless and mobile wallet payments?
Yes, if your terminal or POS setup supports the applicable contactless payment methods and card networks.
Can credit card processing integrate with my existing POS system?
Sometimes. Compatibility depends on the POS vendor, processor, gateway, and available integrations. Confirm support before switching providers or purchasing hardware.
Is credit card processing secure?
Modern systems offer important safeguards, but security depends on implementation and ongoing merchant practices. Ask about encryption, tokenization, EMV support, fraud controls, and PCI DSS obligations.
Can I switch processors without replacing all my equipment?
It depends on whether your existing hardware and software can be reconfigured or certified for the new provider. Some terminals and POS platforms are locked to specific processing relationships.
Make Every Payment Work Harder for Your Business
Your payment system should support convenient checkout, clear financial visibility, and technology that fits how you operate. Whether you are comparing rates or planning a POS upgrade, start with a review of your current needs and the full cost of your options.
Ready to review your credit card processing? Talk with the Gratitude Merchant team about your current setup, processing costs, and payment technology goals. Explore options tailored to how your business accepts payments.